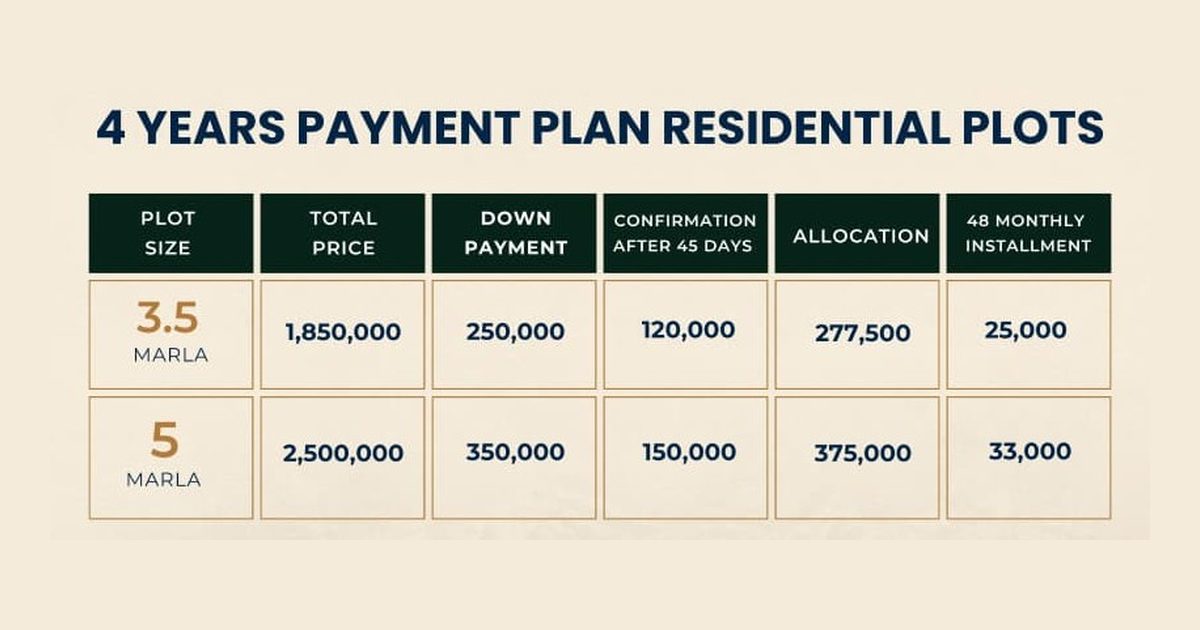
The structure is identical, only the numbers change
Royal Swiss City currently publishes prices for two plot sizes. 3.5 Marla and 5 Marla. Phase 1 also has 10 Marla (PKR 4,750,000) and 1 Kanal (PKR 9,000,000) plots, quoted by the developer with no instalment plan published yet, and there is no 3 Marla plot. Both follow the exact same four step plan. First, a down payment to book the plot. Then a confirmation payment 45 days later. Then an allocation charge once a specific plot is assigned to you. Then 48 equal monthly instalments until the full balance clears.
3.5 Marla, the entry point
A 3.5 Marla plot is priced at PKR 528,572 per Marla. The total comes to PKR 1,850,000. The down payment is PKR 250,000. The 45 day confirmation payment is PKR 120,000. The allocation charge is PKR 277,500. The monthly instalment across 48 months is PKR 25,000.
Add those four numbers together. Down payment, confirmation payment, allocation charge, and 48 months of instalments. The sum should land close to the published total. That simple check is worth running on any payment plan you are shown, developer published or otherwise, since it catches quiet errors or misquotes fast.
5 Marla, a step up in size and budget
A 5 Marla plot works out to PKR 500,000 per Marla. That is a lower rate per Marla than the smaller plot, and the total comes to PKR 2,500,000. The down payment rises to PKR 350,000. The confirmation payment rises to PKR 150,000. The allocation charge rises to PKR 375,000. The monthly instalment is PKR 33,000, still across the same 48 month term.
What is not included in either total
Both totals are land cost figures only. Neither one includes development charges. The developer's published terms put them at PKR 300,000 per Marla, which adds PKR 1,050,000 to a 3.5 Marla plot and PKR 1,500,000 to a 5 Marla plot. The billing schedule is not published. Neither total includes a possession or transfer charge that may apply once the scheme is further along. If you are planning your budget month by month, leave room for these extra charges. Do not assume the published total is the full and final cost of owning the plot.
Working out your real monthly commitment
The monthly instalment figure is only part of your real monthly cost. If you plan to hold the plot for years before building, factor in any maintenance or society charges that get introduced once the scheme reaches a later stage. If you plan to build sooner, add construction costs on top of the land price entirely, since none of the figures on this page cover a single brick of actual construction.
Comparing the cost per Marla
Look closely and the 5 Marla plot actually costs less per Marla than the smaller 3.5 Marla plot. PKR 500,000 per Marla against PKR 528,572 per Marla. This is common in plot pricing. Larger plots often carry a lower per unit rate, even though the total price and the monthly instalment both rise. If your budget stretches to the larger plot, you are getting a slightly better rate for the extra land, not just more space for a proportionally higher price.
A note on price changes over time
Prices for early stage schemes rarely stay fixed for years. As a project moves up RUDA's approval ladder, from Technical Approval, which Royal Swiss City now holds, toward Final Sanction, prices typically rise to reflect the lower remaining risk. The figures on this page reflect what was published as of our last check. If you are reading this months after publication, ask the sales office directly whether a new price list has replaced the one shown here, and check the date at the bottom of this post before you assume it is still current.
How a 48 month plan compares to a shorter one
Some housing schemes offer shorter plans, spread over 24 or 36 months, with higher monthly instalments in exchange for a faster payoff. Royal Swiss City's published plan runs 48 months for both plot sizes. A longer plan means a smaller bite out of your monthly budget, which is part of why early stage RUDA schemes often favour this structure to reach a wider range of buyers. It also means a longer period during which you are relying on the developer to keep building and to keep the scheme moving up the approval ladder. Weigh the smaller monthly number against that longer commitment, not just against your monthly income today.
What happens if you miss an instalment
Every housing scheme sets its own rules for a missed or late instalment, and Royal Swiss City's specific penalty terms were not part of the published payment graphic we reviewed. Before you sign anything, ask the sales office directly what happens if a monthly payment is late, whether a grace period applies, and whether a missed payment can affect your allocation. Get the answer in writing rather than relying on a verbal assurance, since this is exactly the kind of term that matters far more once you are several years into a 48 month commitment than it does on the day you book.
Three questions worth asking before you sign anything
First, ask whether the figures you are shown match what is published here and on the developer's own materials. Prices in this corridor have moved before, and they can move again. Second, ask for a written receipt and an allocation letter at every single payment stage, not only the first one. Third, if you are paying from overseas, confirm the accepted payment channel and the required documents before you send any funds. These requirements can shift between one booking round and the next.
Putting the numbers next to your own budget
Before you book, write out your own monthly budget on paper, not just in your head. Take your current fixed costs, rent, utilities, food, transport, and existing loan payments if any. Subtract that total from your monthly income. Whatever remains should comfortably cover the instalment you are considering, with room left over, since a 48 month commitment is a long time to carry with no margin for a slow month at work or an unexpected expense. A plot is not worth the stress of missing a payment you could have avoided by choosing the smaller size first.
We update this post whenever the developer publishes new pricing, or a new plot size. Every update carries a date, so you always know exactly how current the numbers in front of you actually are.